What’s driving U.S. stock record highs?
Discover why U.S. stocks continue to outperform despite ongoing tensions in the Middle East and softened economic data.
Cooling data, hotter market
U.S. data gave markets something close to a Goldilocks combination last week. U.S. inflation cooled following weaker jobs data, but there is still little evidence of a broader downturn.
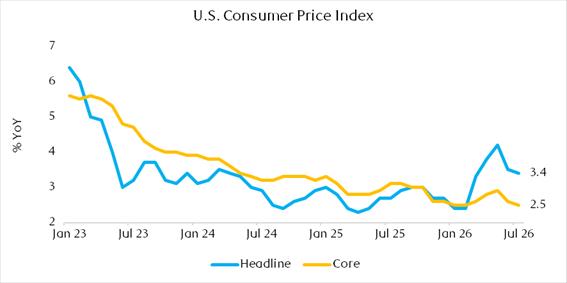
The July headline Consumer Price Index (CPI) rose just 0.1% over the month, taking annual inflation down to 3.4% from 3.5%. More importantly, core inflation rose 0.2%, with the annual rate easing to 2.5%. This was reassuring after surging oil prices raised fears that inflation could reaccelerate.
Source: Bloomberg
There were some yellow flags beneath the surface. Core goods prices accelerated and services inflation also remains sticky.
But producer prices provided relief. The headline Producer Price Index (PPI) was unchanged in July, contradicting expectations for an increase, while the annual rate slowed to 4.7% from 5.5%. This suggests the pipeline inflation pressure is weaker than feared.
Taken together, CPI and PPI have reduced the urgency for the Federal Reserve (the Fed) to immediately raise interest rates again.
This comes after last week’s surprisingly weak jobs report, which showed the U.S. economy lost 23,000 jobs in July. Retail sales also contracted in July, which provided another important test of consumer momentum.
Interestingly, markets currently seem comfortable with a little weakness in U.S. data as investors still see resilience rather than recession.
That distinction is important. The broader economy remains resilient and crucially, corporate profits are exceptionally strong. Some moderation in employment and consumer spending can be helpful for markets if it takes pressure off the Fed.
Markets sharply reduced the probability of a September rate hike following the inflation data, although an increase later this year remains possible.
For equities, that is a relatively favourable combination: growth is cooling enough to give the Fed room to wait, but not enough to derail corporate profits.
However, oil continues to be the obvious challenge to this Goldilocks scenario.
Markets learn to live with Hormuz
Developments surrounding the Strait of Hormuz remain one of the biggest macro risks facing markets given the unprecedented supply shock, but investors have become noticeably less reactive to each new headline.
The conflict remains unresolved and the Strait continues to face severe disruption. The U.S. has intensified its threats towards Iran, while Washington is preparing what Treasury Secretary Scott Bessent has described as “unprecedented additional economic measures” against Tehran.
President Donald Trump has alternated between a more conciliatory tone and renewed threats of pressure, creating occasional flare-ups in oil prices. Brent crude oil has nevertheless remained around the high-$80s per barrel, well below its earlier wartime peaks.
A renewed surge in oil would of course be a concern. It could push inflation higher again and potentially force the Fed back towards tightening.
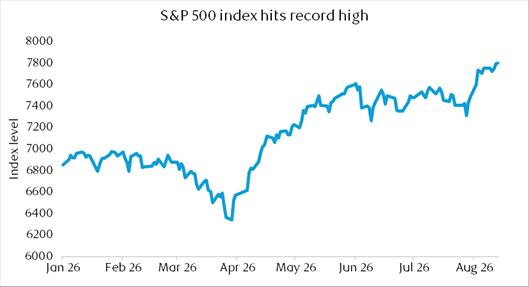
Despite this uncertainty, the S&P 500 reached record highs.
Source: Bloomberg
There is an element of geopolitical fatigue here. After months of U.S.-Iran tensions, markets are becoming more immune to individual headlines. Unless an escalation materially changes the outlook for energy supply, inflation or economic growth, investors appear increasingly willing to look through it.
Ultimately, fundamentals matter more. And right now, those fundamentals remain supportive.
Earnings give the bull market firmer foundations
The second-quarter U.S. earnings season has been extraordinary.
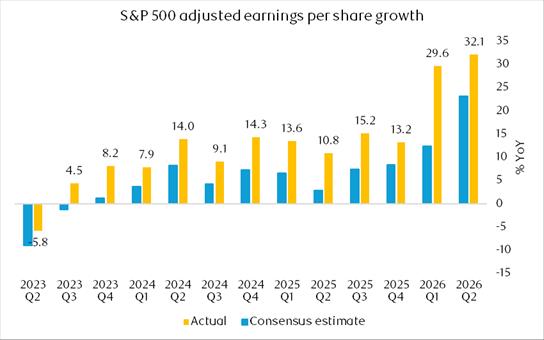
With almost 90% of the S&P 500 having reported by the end of last week, blended earnings growth stood at 50.4% year-on-year. That headline earnings growth number is inflated by hyperscalers’ investment gains from SpaceX, Anthropic and Open AI. Adjusting for those exceptional items that are not related to underlying business operations, S&P 500 earnings growth was still around 32%.
The strength of corporate America is not simply an accounting effect or an AI story.
Source: Bloomberg
At the same time, we are seeing more evidence that enormous investment in AI is translating into revenue and profit. Cloud demand specifically tied to AI has boomed, semiconductor earnings have surged and AI-related infrastructure spending continues to feed through the broader economy.
Perhaps even more encouraging is the broadening of the rally. Technology remains a major earnings engine, but profit growth is becoming less concentrated. That gives the bull market a healthier foundation than one driven purely by a handful of mega-cap stocks and rising valuations.
There are still risks. Expectations for AI are extremely high, valuations leave less room for disappointment, capital expenditure continues to rise rapidly, and free cash flow from hyperscalers have deteriorated.
But for now, the combination of strong earnings, improving AI monetisation and broader participation in profit growth gives investors a fundamental reason to remain constructive.
That also explains why markets have been able to absorb softer economic data and persistent geopolitical uncertainty. The macro backdrop may be cooling, but corporate America is not.